Quick Answer
What happens to leased solar panels when you sell your Oahu home?
Depending on what the lease or power purchase agreement allows, your buyer can take it over or you can buy it out before closing. Fannie Mae says the value of leased panels, or panels under a power purchase agreement, cannot be included in the appraised value, while owned panels follow its standard appraisal requirements. A fixture filing on the panels is filed in the office where mortgages are recorded, so it can show up on your title report. Hawaiian Electric says a buyer of a home with rooftop solar assumes all the rights and responsibilities of the previous owner’s existing agreement with the utility’s solar program.
By Aksana Tupalskaya
The question is not whether solar is good or bad for resale. The question is which structure you are sitting on, and what it does to the appraisal, the title report, and your buyer’s loan approval.
Owned, Financed, or Leased: What Your Title Report Says
A rooftop system is commonly held one of three ways. You own it outright. You own it but a separate solar loan is attached to it. Or a third party owns it and you pay that company under a lease or a power purchase agreement.
Fannie Mae puts the burden on the lender to figure out which one it is. Its Selling Guide makes lenders responsible for determining the ownership and any financing structure of the panels in order to underwrite the loan and maintain first lien position, and it requires the lender to review the title report. Where documentation is insufficient and ownership is unclear, no value for the panels may be given on the appraisal unless the lender gets a UCC personal property search confirming that no non-mortgage lender claims the panels as collateral.
That title review is where Oahu sellers can get surprised. A solar company that finances panels can protect its interest with a UCC-1 fixture filing, and under HRS 490:9-501(a)(1) a fixture filing goes in the office that records a mortgage on the related real property. Mortgages in Hawaii are recorded in the Bureau of Conveyances under HRS 502-83, so the filing lands in the same records as your mortgage.
Fannie Mae says that, if properly filed, the security interest in the fixture has priority over the lien of a mortgage recorded after it, and that a fixture filing in the land records with priority senior to the new mortgage must be subordinated.
| How the system is held | What it does to the appraisal and the title report | What has to happen before closing |
|---|---|---|
| Owned outright, paid cash | Fannie Mae’s standard appraisal, insurance, and title requirements apply, and any contributory value follows its appraisal rules. | Hawaiian Electric says a buyer assumes the previous owner’s existing agreement. |
| Owned, rolled into your first mortgage | Same as owned outright under Fannie Mae’s rules. | No separate solar debt; the panels are secured by your first mortgage. |
| Owned, separate solar loan with a UCC-1 fixture filing | Fannie Mae says separately financed panels must not contribute to value unless the documents show the panels cannot be repossessed on default. | If the fixture filing is in the land records with priority senior to the buyer’s new loan, Fannie Mae says it must be subordinated. |
| Leased from a third party | The value of the panels cannot be included in the appraised value. The monthly lease payment is counted in your buyer’s debt ratio unless the lease is a fixed payment for a set amount of energy with a production guarantee. | As the lease allows, your buyer takes it over, or you buy it out and the system becomes owned. |
| Power purchase agreement | No value in the appraisal either. A payment calculated solely on the energy produced may be excluded from the buyer’s debt ratio. | As the agreement allows, your buyer takes it over or you buy it out. |
The Three Paths a Seller Actually Has
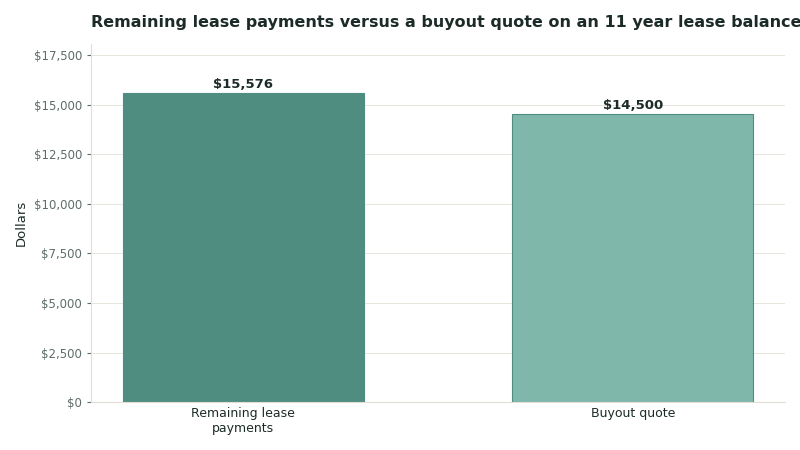
Buy the lease out. If your agreement offers a buyout, get the quote in writing and compare it to what is left on the agreement. Take a hypothetical twenty-year lease with eleven years to run at $118 a month. That is $15,576 of payments still attached to your roof. If the buyout comes back at $14,500, you are not saving much in raw dollars, but you are converting the system from something the appraiser must ignore into something the appraiser can consider, and you are ending a payment that Fannie Mae counts in your buyer’s debt ratio unless the lease is a fixed payment for a set amount of energy with a production guarantee. Those two effects are the real return on a buyout, not the arithmetic.
Transfer it. Your buyer takes over the lease or power purchase agreement if its terms allow. On the utility side, Hawaiian Electric says a buyer of a home with rooftop solar assumes all the rights and responsibilities of the previous owner’s existing agreement and can remain enrolled in that program. If the lease on the system has changed, Hawaiian Electric may ask for documentation.
Price around it. Disclose the agreement up front, put the full lease or power purchase agreement in the listing packet, and let buyers price the payment into their offer instead of discovering it later.
Every figure above is a mechanism, not a quote for your house. Run your own numbers before you commit to a path. If you are deciding what else to touch before listing, my breakdown of what is worth renovating before you sell a Kailua home uses the same test: does the dollar you spend change what an appraiser or a lender can count? And if property tax is part of your math, here is what the Oahu home exemption actually saves.
Frequently Asked Questions
Do leased solar panels lower my Oahu home’s value?
Fannie Mae’s guide says the value of leased panels, or panels under a power purchase agreement, cannot be included in the appraised value. The system adds nothing to the appraisal, while a lease payment counts in your buyer’s debt ratio unless the lease is a fixed payment for a set amount of energy with a production guarantee.
Does a solar lease show up on my title report?
The lease itself is a contract. A UCC-1 fixture filing, when a solar company files one, is filed in the office where mortgages are recorded, which in Hawaii is the Bureau of Conveyances under HRS 490:9-501 and HRS 502-83. That is why it surfaces in the title search. Order a title report early if you think a system was financed or leased.
Does the new owner keep my Hawaiian Electric solar program?
Yes. Hawaiian Electric says a buyer of a home with rooftop solar assumes all the rights and responsibilities of the previous owner’s existing agreement, which lets the buyer remain enrolled in that program.
More resources on this topic
Staging an Oahu Home You Can't See in Person: What Remote Sellers Should Know.
Moving Off Island and Renting Out Your Oahu Home? What the Tax Bill Does Next.
What Is a CPR Property on Oahu, and Why Do Some Sell Better Than Others?
Leased or owned, the decision comes down to one question: are you converting that system into something a lender and an appraiser can count, or are you handing your buyer a payment and a filing on the title report? I track what Oahu homes actually closed at after seller credits, not what the portals show, and that is the only honest baseline for pricing a house with solar on it. Grab the free monthly sold report at my sold report page.